Daily Briefing
Market Briefing, Oct 23 2026: AI Funding Fears Weigh on Chips as Oil Jumps on Iran Report
~7 min readAlertsify Team
Market Briefing, Friday, October 23, 2026
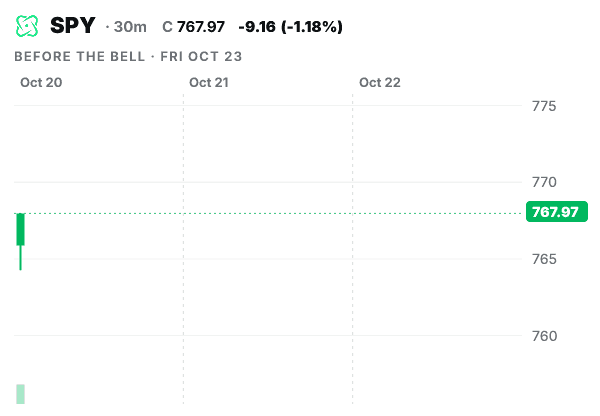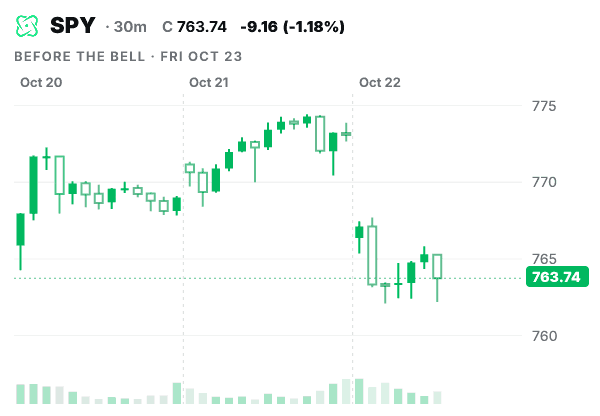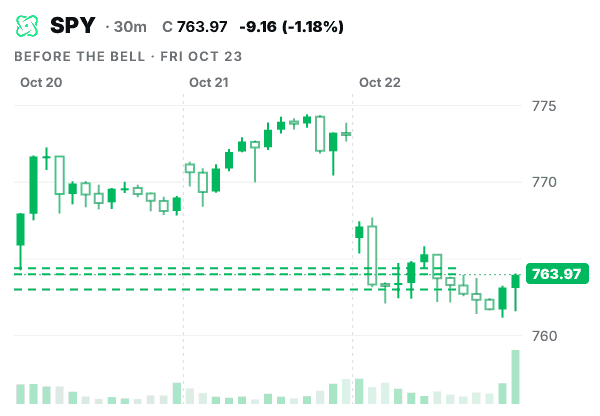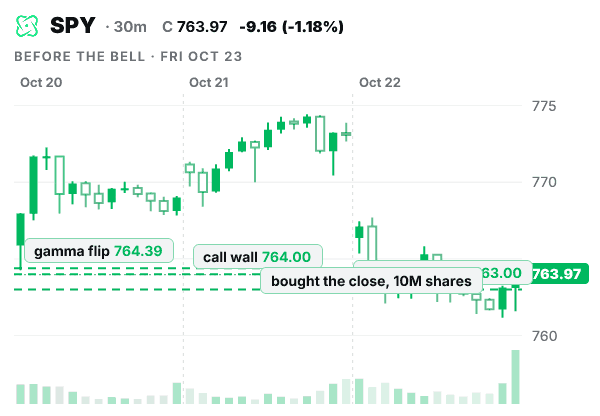
Futures are drifting lower after a sharp selloff in AI-linked stocks over concerns about the sector's massive funding requirements . Oil spiked and stocks and yields sagged after a report that the U.S. and Israel might resume attacks on Iran next month , and Meta's heavy spending outlook and chip worries also hurt. Options flow from yesterday's session leaned heavily bearish in META, SPCX, SMH, MU, NVDA and AMD. Today depends on the 9:45 flash PMIs, the 10:00 Michigan final reading and how American Express's print is received, all with the Fed's meeting, followed by the Core Personal Consumption Expenditures (PCE) Price Index coming next week.
Market setup
| S&P 500 futures | -0.14% |
| Nasdaq 100 futures | -0.03% |
| Dow futures | -0.30% |
| Russell 2000 futures | -0.23% |
| 10-year Treasury yield (near a one-month low after Thursday's haven bid) | 5.03% |
| WTI crude | $100.90 (+1.4%) |
| Bitcoin | $81,690 (-3.43%) |
| Gold (spot, after hitting fresh three-month lows at $3,986 ) | $4,024 |
Key levels (dealer gamma)
| SPY (spot ~764) | Unavailable today |
| QQQ (spot ~704) | Unavailable today |
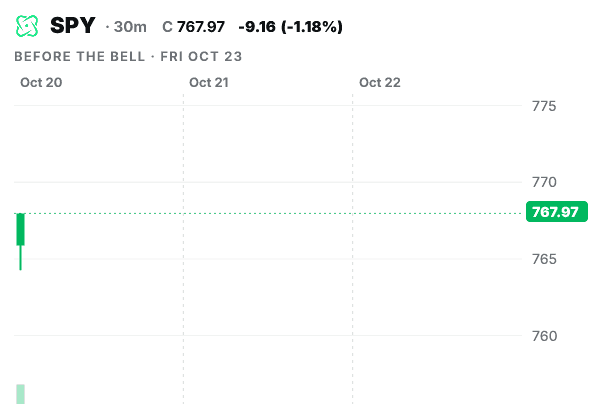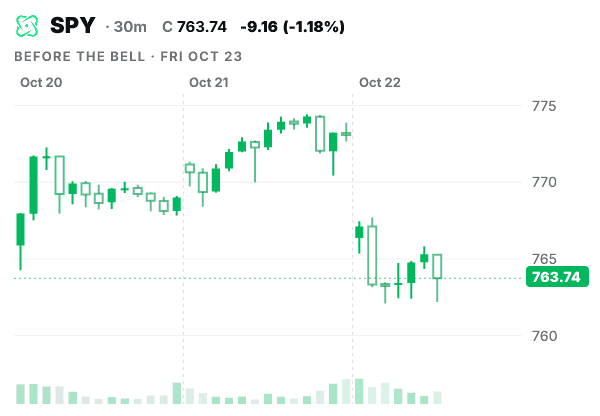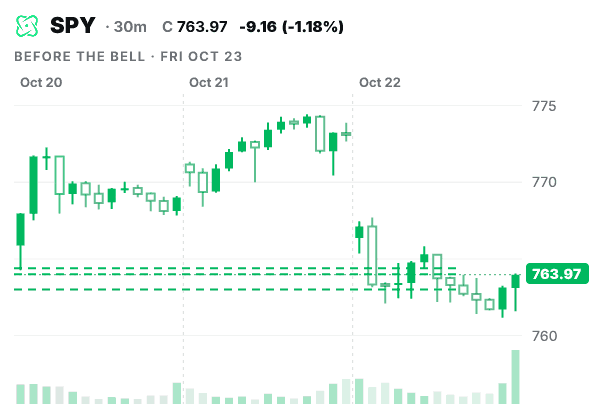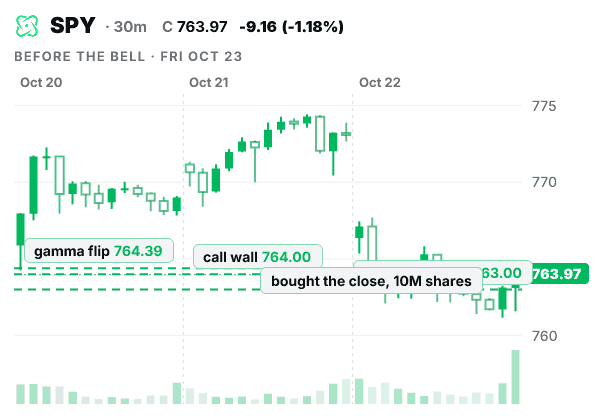
We couldn't get verified, current dealer positioning for this morning, so we're not printing walls rather than guessing. When we have the data, call walls show where dealer hedging may slow a rally and put walls show where hedging may cushion a dip. They're estimates of positioning, not guarantees.
Today's market calendar (ET)
| 8:30 AM — American Express earnings call | Call 8:30 |
| 9:45 AM — US Flash Manufacturing PMI (Oct); our prior reading is 57 | Est. 55.5 |
| 9:45 AM — US Flash Services PMI (Oct); our prior reading is 58.7 | Est. 58.0 |
| 9:30 AM — SLB earnings call | EPS est. $0.62 |
| 10:00 AM — University of Michigan final consumer sentiment (Oct), including inflation expectations; we found no consensus | Prior 48.1 |
Notable earnings
Already reported: American Express (AXP) said third-quarter consolidated total revenues net of interest expense were $20.1 billion, up 9 percent year-over-year , roughly in line with the $20.12B estimate. Its GAAP profit of $5.42 per share was 20.4% above analysts' consensus estimates. The third-quarter net write-off rate was 1.8 percent, down from 1.9 percent a year ago. In the prior evening's reports, Deckers Brands (DECK) reported earnings of $2.03 per share on revenue of $1.48 billion against $1.82 per share on revenue of $1.51 billion expected. Sallie Mae (SLM) reported a loss of $0.19 per share . Premarket, gold miner Newmont fell 1.5% after reporting quarterly results and warning that unit costs are expected to trend higher in 2027.
Still ahead before the open: SLB (EPS est. $0.62), Infosys (INFY, $0.21), First Citizens (FCNCA, $46.61) and Rogers (RCI, $0.86), per consensus . Also on the slate: Autoliv (ALV, est. $2.23), Rithm Capital (RITM, $0.50), Flagstar (FLG, $0.07), Gentex (GNTX, $0.50) and First Hawaiian (FHB, $0.59) , along with Booz Allen Hamilton (BAH).
After the close: It's a thin Friday slate: TowneBank (TOWN, est. $0.83) and Columbia Financial (CLBK, est. $0.15) , plus RCBC . We couldn't find options-implied expected moves for any of these small-cap banks today, so none are listed.
Congress corner
- Rep. Rick Larsen (D): buy WSM, $1K–$15K, traded Oct 8; sell HD, $1K–$15K, Oct 8; buy ADI, $1K–$15K, Oct 8
- Rep. Kevin Hern (R): sell NEE, $15K–$50K, traded Oct 2
- Rep. Gilbert Cisneros (D): buy BHE, $15K–$50K, traded Oct 1
- Rep. Ro Khanna (D): sell SNPS, $1K–$15K, traded Oct 1 , plus small sales of DASH, ITW and LVS the same day
- Rep. Michael A. Rulli (R): sell WFC, $1,001–$15,000, traded Sep 3
These are delayed STOCK Act disclosures, not real-time trades. Trades are due within 45 days, but some are filed months or even years later, so check each trade date.
Social-media trends
Retail sentiment is defensive. Sentiment toward the SPDR S&P 500 ETF (SPY), which tracks the S&P 500, trended in 'extremely bearish' territory over the past day. GOOGL is the top trending ticker, and traders [are] focused on whether heavy AI and data-center spending will produce enough growth and returns ahead of next week's report. MRNA, SOXL and Bloom Energy (BE) are also crowded, with BE dropping as much as 2% premarket after plunging nearly 9% on Thursday . SpaceX (SPCX) chatter keeps building: mentions of SpaceX have surged by an impressive 67% . Metals are drawing traffic too, with the silver ETF in focus among retail traders amid a sharp selloff . Nokia, Walmart and Schwab round out the trending list.
What matters today
- Worries over AI funding hit chips hard. Meta drove Thursday's selloff. The company disclosed lease agreements and other non-cancelable AI commitments totaling $825 billion, up from $700 billion in July. Its third-quarter free cash flow also swung to a $2.1 billion deficit. AMD fell 8.1% and Nvidia 4.4%, while the Philadelphia Semiconductor Index dropped 6.7%, its worst decline since June. Options flow matched the selling: net premium was -$151.5M in META, -$105.3M in SMH, -$89.9M in MU, -$87.7M in NVDA and -$75.4M in AMD. One premarket check showed Meta, Nvidia and AMD recovering after Thursday's sell-off . Trading impact: watch whether the early bounce in semis holds or fades once cash trading opens at 9:30.
- Money moved into defensive sectors. Staples (XLP) led yesterday at +3.31% and utilities (XLU) gained +2.07%. Tech (XLK) fell -3.29% and communication services (XLC) lost -1.42%. Investors dumped high-growth communication services and technology stocks and flocked to the safety of defensive sectors and safe-haven U.S. Treasuries. Trading impact: a second straight day of staples and utilities leading would show the move away from tech is continuing, not just a one-day flinch.
- Brent oil above $113 on Middle East risk. Brent crude settled at $113.17 a barrel, up $4.35 (4.00%), its highest level since May. The jump came after fresh attacks by Iran-backed Houthis on Saudi Arabian energy facilities and airports , along with a report that the U.S. and Israel plan renewed strikes on Iran after the midterms . U.S. oil is up 72% in 2026 and Brent is up 83%. Oil was rising again in early Asia trading. Trading impact: crude headlines over the weekend may make traders less willing to hold risk into Friday's close.
- Treasury yields fall, PMIs due at 9:45. The 10-year Treasury yield fell 19.3 basis points to 4.953%, its largest daily drop since March 10, 2023. Futures now price a 7.2% chance of a rate hike of 25 basis points or more, down from 27.7% a week earlier and 55.4% a month ago. The Fed meets October 27–28. The flash Services PMI (prior 58.7) and Manufacturing PMI (prior 57) come out at 9:45 AM ET, followed by final U. Michigan sentiment (prior 48.1) at 10:00 AM ET. One-year inflation expectations in that survey are forecast at 4.7%. Dealer positioning data is unavailable today. Trading impact: strong PMIs or higher inflation expectations could quickly undo the bond rally and put a rate hike back on the table.
- Earnings beats aren't lifting stocks. Western Digital was 0.90% lower in premarket trading despite beating estimates, with quarterly earnings of $4.64 per share on $4.38 billion in revenue versus $4.07 and $4.13 billion expected. Deckers dropped 7% after revenue of $1.48 billion missed the $1.51 billion estimate. Before the open, American Express reported third-quarter revenue of $20.1 billion, up 9 percent from a year ago . Its GAAP profit of $5.42 per share was 20.4% above consensus. Options flow in BAC also leaned bullish at +$19.7M net premium. Trading impact: beat-and-sell reactions in AI hardware stocks, set against strength in financials, will show where investors want to be heading into next week's Microsoft and Alphabet reports.
Options flow
| PSIX $45 P 11/20 — volume of 2,591 against open interest of 84 means most of this is new positioning . The stock is up $4.28 to $47.57 . | 2,591 @ $3.70 ask-side |
| QQQ $696 P 10/30 — open interest in this strike jumped after Thursday's deterioration in the broader market . | +1,386% open int. |
| META net flow, all contracts — the largest net-bearish options flow of the session, after earnings left the stock -6.98% because Q3 free cash flow was a $2.12B deficit . | -$151.5M net |
| MU net flow, all contracts — on wider screens, MU grew from $158.35 million to $260.71 million in bearish-classified premium . | -$89.9M net |
| KLAC net flow, all contracts — one of the few chip names with net-bullish flow. It also made the $1M+ bullish list at $31.95M . | +$9.3M net |
| Data note — we don't have strike-level prints or fill side for the net-flow names today. Those rows show net premium across all of each name's contracts. | Strikes n/a |
Alertsify is copy trading software for options and stocks, not an RIA or broker-dealer. This post is for information only and is not investment advice.
More from the blog
Daily Briefing
Market Briefing, Oct 22 2026: Meta Beats, Tesla Cuts Capex, Futures Slide on Oil
Futures fell before the bell as Brent crossed $110 after a drone strike on a Saudi oil field and the 10-year yield sat above 5.1%. Meta beat expectations while Tesla cut its capex guidance to about $20 billion.
Daily Briefing
Chips Crack Again, Even After a Beat — Market Briefing, October 15, 2026
Hot CPI, a six-day chip rout, TSM's beat-and-fade, and a closed Strait of Hormuz collide ahead of a packed PPI/retail sales/bank-earnings Thursday.
Daily Briefing
Market Briefing, October 14, 2026: CPI Day With Gamma Pinned at Spot
September CPI lands at 8:30am ET with six companies reporting before the bell, while SPY's dealer gamma call and put walls sit almost on top of spot.