Daily Briefing
Market Briefing, Nov 2, 2026: Tech Selloff Meets a Rebound Bid Ahead of Apple and Palantir Earnings
~6 min readAlertsify Team
Market Briefing, Monday, November 2, 2026
Tech led Friday's selloff: XLK fell 4.89% while energy and staples gained. Options flow was heavily bearish too, with net call premium at -$792.7M, mostly in NVDA, SNDK, SPCX, INTC and MU. Overnight, US equity futures advanced to halt a bruising selloff in the artificial intelligence trade, with falling oil prices helping stocks to start the month on a positive note. Today depends on the 10:00 AM ISM manufacturing report and on Apple and Palantir after the close. Behind that sits a crowded week: a packed week of earnings, midterm elections, and a key jobs report.
Market setup
| S&P 500 futures | +0.46% |
| Nasdaq 100 futures | +0.77% |
| Dow futures | +0.51% |
| Russell 2000 futures | +0.68% |
| 10-year Treasury yield | 4.93% (-6 bp) |
| WTI crude (falling as Iran–Qatar talks continue) | $100.62 (-3.4%) |
| Bitcoin (recovering after weekend Binance security event) | ~$79,000 |
| Gold | $3,912 (+0.34%) |
Key levels (dealer gamma)
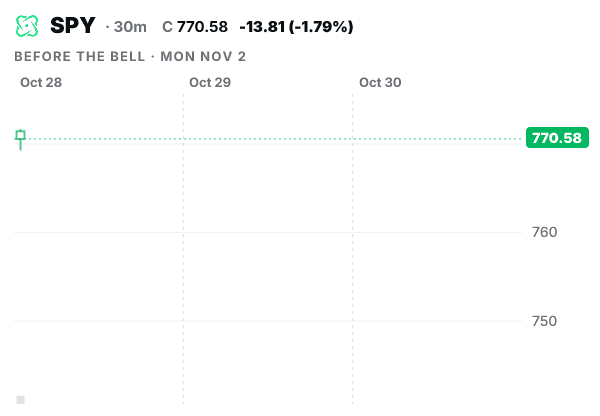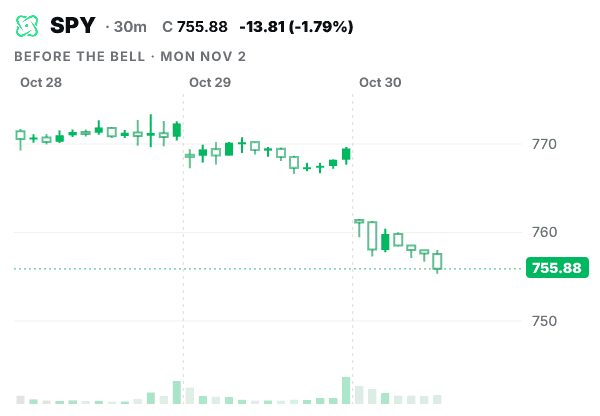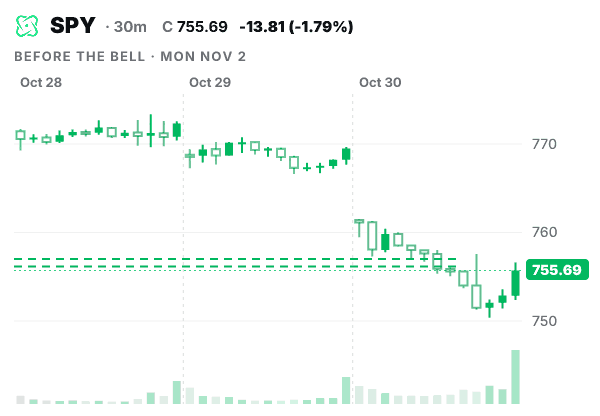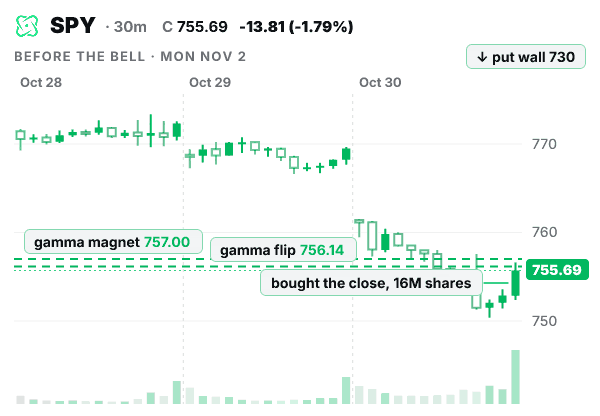
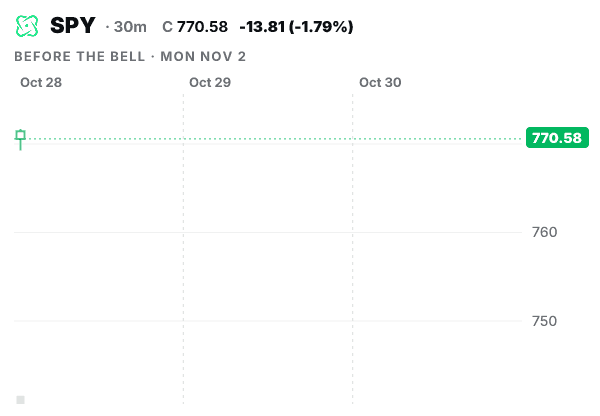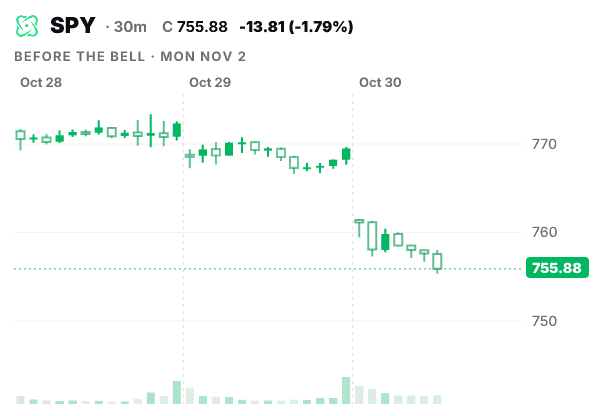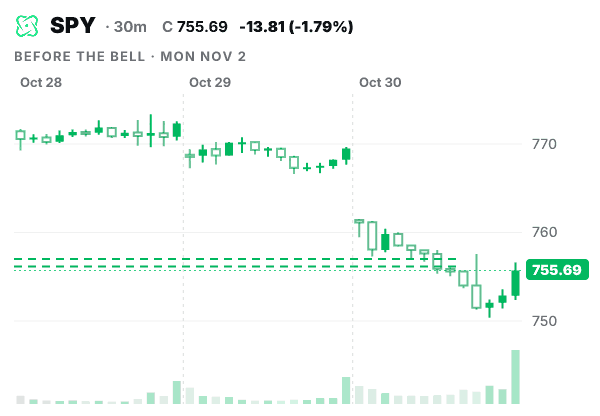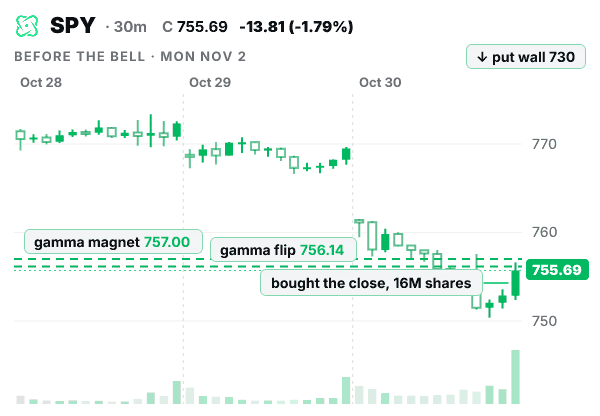
| SPY (spot ~761) | Call wall 770 (then 800) · Put wall 755 (then 750) |
| QQQ (spot ~697) | Call wall 720 (then 800) · Put wall 695 (then 680) |
Call walls mark strikes where dealer positioning may slow a rally. Put walls mark strikes where dealer hedging may cushion a dip. These levels come from several public estimates, and some are a few days old. Both SPY and QQQ are trading below every gamma flip, with net 40-day gamma deeply negative , which can make moves bigger in either direction. They are positioning estimates, not guarantees.
Today's market calendar (ET)
| 9:45 AM | US Mfg PMI · prior 55.9 |
| 10:00 AM | ISM Mfg PMI · fc 54.5 (prior 54.5) |
| 10:00 AM | Construction Spending · fc 0.4% (prior 0.9%) |
| After 4:00 PM | Apple, Palantir earnings |
| 5:00 PM | Apple & Palantir calls |
Notable earnings
Already reported: We had no confirmed results from this morning's slate at press time.
Still ahead before the open: Consensus EPS estimates: Check Point Software · CHKP · 2.48 ; Estee Lauder · EL · 0.51 ; IDEXX Labs · IDXX · 3.72 ; Marriott · MAR · 2.85 ; Public Service · PEG · 1.19 ; Tempus AI · TEM · -0.09 . Some of these may hit the wire before you read this.
After the close: Apple ±4.3%: options expiring Nov. 4 implied a move of about 4.3% , and Wall Street expects Apple to report earnings per share (EPS) of $1.99 . This is its first under John Ternus as chief executive. Palantir ±13.3%: the options market is pricing in about a 13.3% move in either direction . Palantir forecasts $2.16 billion in Q3 revenue , and the EPS consensus is $0.41.
Congress corner
- Rep. David Taylor: Buy LRCX, $1K–$15K, traded Oct 15, 2026 (reported Oct 29)
- Rep. David Taylor: Buy T and Buy PLD, $1K–$15K each, traded Oct 15, 2026
- Rep. David Taylor: Sell MPC and Sell V, $1K–$15K each, traded Oct 15, 2026
- Rep. Rick Larsen: Buy WSM, $1K–$15K, traded Oct 8, 2026; Sell HD and Sell FDX, $1K–$15K each, same date
These are delayed disclosures, not real-time trades. Congress members have 45 days to report trades after they occur, so there may be a lag between when a trade happens and when it appears .
Social-media trends
Retail chatter is focused on the beaten-down AI and chip names that also drove Friday's bearish options flow. Intel is still a hot topic after the stock plunged 24% over the week after the chipmaker issued a weak Q4 forecast. SPCX is moving overnight on reports that Musk revived TSMC Terafab talks. Even so, retail sentiment for SPCX slipped to 'bearish' from 'extremely bullish' levels a week ago . Palantir is near the top of trending lists ahead of tonight's report. Crypto-linked names are also back in focus: $COIN and $MARA stabilize pre-market as Bitcoin recovers toward $79,000 .
What matters today
- AI Sell-Off Meets a Rebound Bid. On Friday, the S&P 500 lost 140.32 points, or 1.82%, to 7,580.07 and the Nasdaq Composite lost 747.73 points, or 2.86%, to 25,437.00 . Intel shares plunged 28.6% . In our sector data, XLK was the worst sector at -4.89%. XLE (+1.91%), XLP (+1.41%) and XLU (+0.67%) led, as money rotated into defensive sectors. This morning, Nasdaq-100 contracts are up 0.8% after the index briefly entered a correction . In premarket, Micron rose about 2.7%, SanDisk gained over 3%, and SK Hynix climbed nearly 5% . Trading impact: chip and mega-cap tech will show whether today's bounce holds after Friday's losses.
- Options Flow Still Leans Bearish on Semis. Market tide shows net call premium at -$792.7M and net put premium at +$151.8M. The biggest drags were NVDA (-$100.1M), SNDK (-$85.0M), SPCX (-$80.2M), QQQ (-$78.5M), INTC (-$74.5M) and MU (-$71.5M). The few positive names included SPY (+$24.2M), MRVL (+$22.6M) and IWM (+$18.6M). Dealer gamma positioning data is unavailable today. Trading impact: option flows in the same chip names now bouncing premarket are still bearish, so a hesitant rebound is possible.
- Apple and Palantir Report After the Close. Apple reports its first earnings under CEO John Ternus . Analysts expect EPS of $1.98 on revenue of $113.27 billion , and Apple was the only Magnificent Seven stock to fall in premarket trading ahead of its results . Palantir is expected to report an EPS of $0.41 on revenue of $2.18 billion , and ON Semiconductor and Vertex also report tonight. Trading impact: after-hours moves in AAPL and PLTR will set the tone for big tech going into AMD's report on Tuesday.
- Oil Drops on Iran Talks Ahead of the Midterms. Brent crude oil futures declined by $3.68, or 3.2%, to $109.75 per barrel early today, after Iranian and Qatari officials held a third straight day of talks aimed at pushing for a deal to end the U.S.-Israeli war on Iran . Brent remains approximately a $47 rise over the past year . One analyst warned that tougher rhetoric could push Brent toward $120 after the midterm elections , which are on Tuesday. Trading impact: energy led Friday's session, so lower crude could weigh on XLE while easing inflation worries for the broader market.
- ISM Data Starts a Week Focused on a December Rate Hike. The S&P Global Manufacturing PMI comes out at 9:45 AM ET (prior 55.9). ISM Manufacturing follows at 10:00 AM ET (forecast 54.5, prior 54.5), alongside Construction Spending (forecast 0.4%, prior 0.9%). The Federal Reserve held its benchmark rate at 3.75–4.00% on 28 October but two of its voters dissented in favour of a rise . Prediction markets now price about a 70% chance of a quarter-point rise at the 8–9 December meeting . Friday's payrolls report is forecast at 55K jobs (prior 29K) with unemployment at 4.2%. Trading impact: a strong ISM reading could raise hike odds and push yields higher, which has been pressuring growth stocks.
Options flow
| NVDA: the largest single drag on the options tide in the prior session, as tech (XLK) finished last among sectors. | -$100.1M net |
| SNDK: memory and storage names had the second-heaviest negative premium on the board. | -$85.0M net |
| SPCX: the third-largest net outflow, putting it ahead of both index ETFs in the tide. | -$80.2M net |
| QQQ: Nasdaq-100 premium leaned negative, while SPY and IWM both drew positive net premium. | -$78.5M net |
| INTC / MU: semis rounded out the negative leaders (INTC -$74.5M, MU -$71.5M), with MRVL a positive outlier at +$22.6M. | -$146.0M combined |
| Contract detail: strike, expiry and ask/bid-side data for individual trades is unavailable today. Figures above are net premium by ticker. | Ticker-level only |
Alertsify is copy trading software for options and stocks, not an RIA or broker-dealer. This post is for information only and is not investment advice.
More from the blog
Education
Live Futures Charts: How to Read ES, NQ, CL and GC for Free
Learn how to read live futures charts for ES, NQ, CL and GC: chart types, timeframes, indicators, rollover and a free charting option with no card required.
Daily Briefing
Market Briefing, Oct 30, 2026: Friday, Oct 30
Friday, Oct 30 What moves the market today, key levels, options flow and the calendar, before the bell.
Daily Briefing
Market Briefing, Oct 29, 2026: Alphabet missed. Nasdaq futures are sliding.
Alphabet missed. Nasdaq futures are sliding. What moves the market today, key levels, options flow and the calendar, before the bell.