Daily Briefing
Market Briefing, Oct 26 2026: Oil Eases as Trump Holds Off on Iran Ahead of Fed Week
~8 min readAlertsify Team
Market Briefing, Monday, October 26, 2026
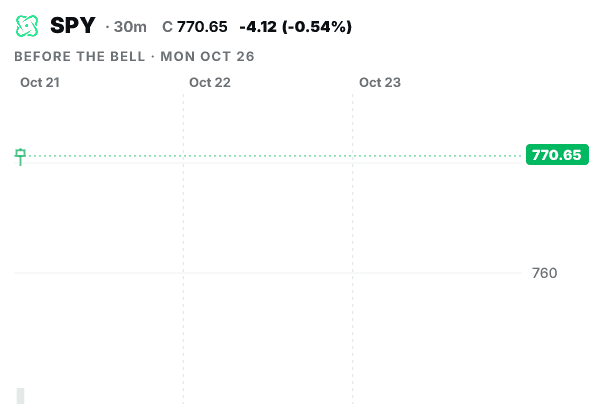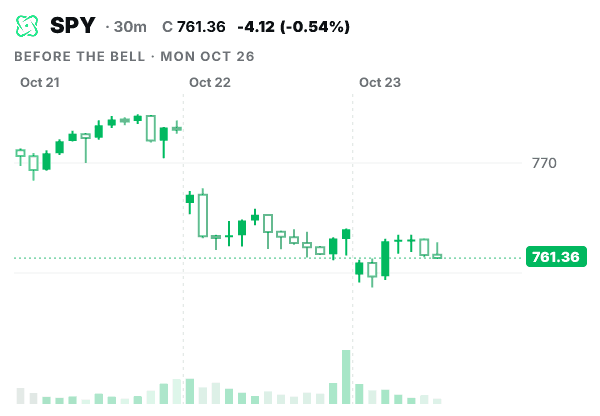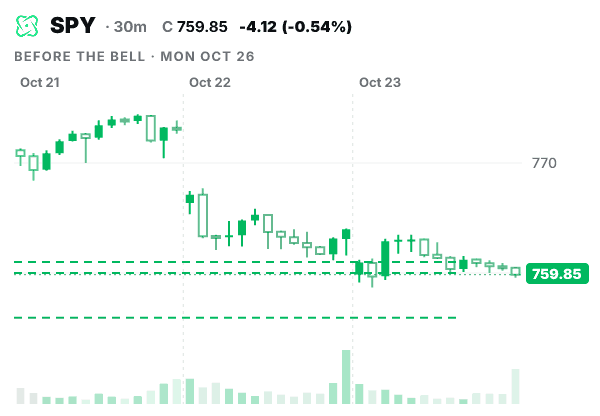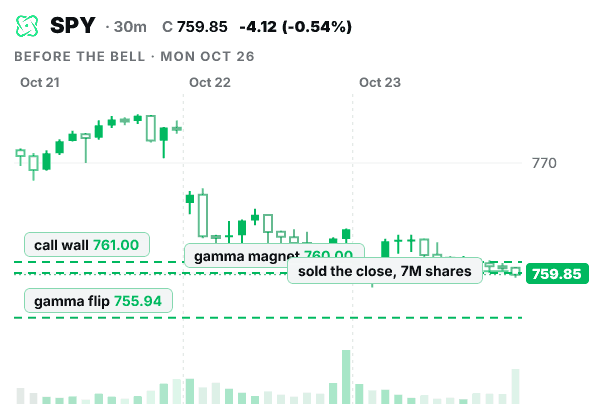
Futures are higher this morning. Cooling crude prices after President Donald Trump ruled out an immediate strike on Iran are helping, and energy was the only standout sector last session. This is the start of a week dominated by corporate earnings and the Federal Reserve's interest-rate decision , but today's calendar is light. That leaves the session hinging on whether oil keeps fading and on Celestica's AI-hardware report after the close. Options flow leans defensive: net call premium is negative, with heavy outflows in AAPL and QQQ, while MU and SPY saw net inflows.
Market setup
| S&P 500 futures ( at 05:19 a.m. ET, S&P 500 E-minis were up 23.25 points ) | +0.3% |
| Nasdaq 100 futures ( up 73 points ) | +0.25% |
| Dow futures ( Dow E-minis were up 257 points ) | +0.49% |
| Russell 2000 futures (we couldn't confirm a pre-market quote this morning) | Not available |
| 10-year Treasury yield ( US 10-year yield at 4.965 ) | 4.965% |
| WTI crude ( fell over 2% as investors weighed the threat of further attacks on Saudi Arabian energy infrastructure against demand worries) | $100.92, -2.28% |
| Bitcoin ( slightly lower on the day, with BTC hovering at the key $80K level ) | ~$80,090 |
| Gold ( edging up after falling about 4% last week, its worst week in over four months ) | ~$4,008 |
Key levels (dealer gamma)
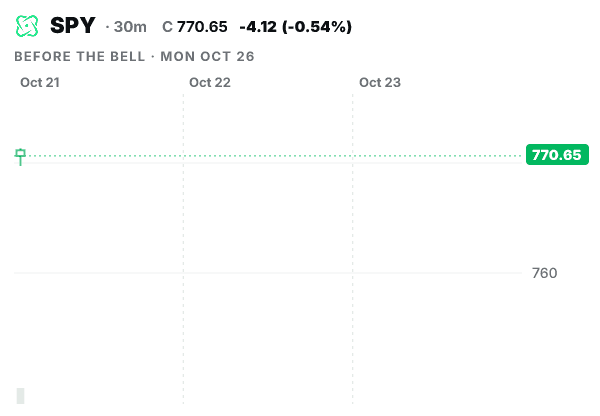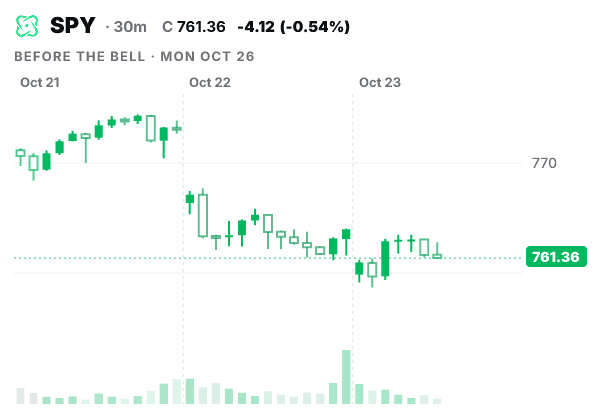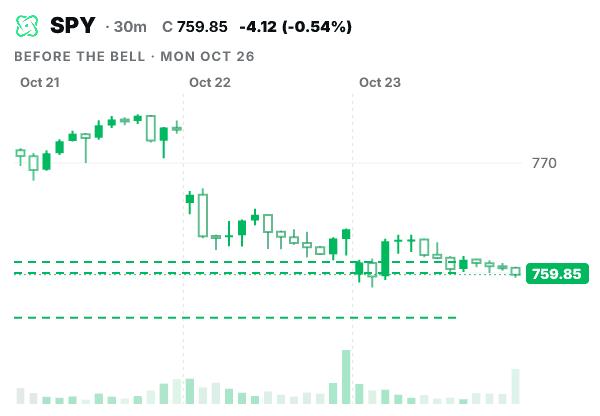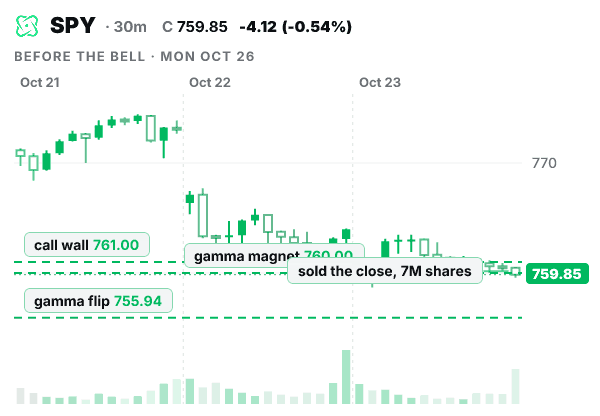
| SPY (spot ~760) | Unavailable today |
| QQQ (spot ~702) | Unavailable today |
Dealer positioning data isn't available today, so we're not listing call or put walls. When we have it, call walls mark where dealer positioning may slow rallies, and put walls mark where hedging flows may cushion dips. These are positioning estimates, not guarantees.
Today's market calendar (ET)
| 8:30 AM | Chicago Fed NAI (Sep) |
| 10:30 AM | Dallas Fed mfg (Oct) |
| 1:00 PM | $69B 2-yr auction |
Times are from the weekly event calendar . We couldn't confirm consensus figures for today's releases, and there are no noteworthy economic reports scheduled for release on Monday, October 26. The bigger events come later this week: the rate decision announced on Wednesday, October 28, 2026, at 2:00 PM ET , then on Thursday third-quarter GDP, September PCE inflation, and consumer spending.
Notable earnings
Already reported: Verizon (VZ) reported its strongest third-quarter postpaid phone net adds in five years, and its best quarterly net account growth in over a decade . Mobility and broadband service revenue of $23.5 billion grew 2.9 percent year-over-year , and the company raised full-year 2026 guidance for key metrics for the third consecutive quarter . It also signed an agreement valued at $2.0+ billion with AWS for distributed AI compute.
Still ahead before the open: Remaining names on the morning slate include ARLP, BFST, BMRC, BOH, CX, DEA, LKFN, MED and MMYT . Consensus estimates include Bank of Hawaii (BOH) at 1.51 and Ensign Group (ENSG) at 1.97 .
After the close: Celestica ±12–15%. The at-the-money straddle for the October 31 expiration prices in a 12-15% move . Wall Street expects Celestica to post earnings of $2.99 per share on revenue of $5.48 billion. Also reporting: Welltower, Cadence Design Systems, Public Storage, Nucor, The Hartford and Celestica , plus Amkor and Rambus. Consensus calls for Nucor (NUE) earnings of $5.84 per share on revenue of $10.84 billion . We couldn't confirm options-implied moves for the other evening reporters.
Congress corner
- Rep. Cleo Fields (D-LA): Buy NVDA, $1K–$15K, traded 1 Oct 2026 ; buy TSM, $1K–$15K, traded 9 Oct 2026
- Rep. Darrell Issa (R-CA): Buy US Treasury note, $5M–$25M, traded 8 Oct 2026 ; sell US Treasury note, $5M–$25M, traded 14 Oct 2026
- Sen. John Boozman (R-AR): Partial sell of MU, $1K–$15K, traded Sep 24, 2026 ; buy CSCO, $1K–$15K, traded Sep 24, 2026
These are delayed disclosures, not real-time trades. Trades are due within 45 days, but some are filed months or even years later, so check each trade date.
Social-media trends
Retail chatter is focused on AI infrastructure and a few big overnight moves. IREN, NBIS, NU and PBR lead the trending lists. Elon Musk's warning that tighter debt markets could drive failures and consolidation among AI neoclouds has fueled selling in NBIS and its peers . On NU, retail sentiment was 'bearish' at the time of writing, with message volume up 300% over 24 hours . SPCX traders are speculating that Cerebras Systems' steep selloff could give CEO Elon Musk an opening to buy the AI chipmaker . Retail sentiment for TSLA flipped to 'bearish' from 'bullish' levels a week ago amid 'high' message volume. On WallStreetBets, Google is the most-mentioned name, with 69 mentions, bullish sentiment , ahead of Wednesday's report. That retail interest lines up with the options tide, where SPCX drew $32.2M in net premium and TSLA saw $22.4M in net outflows.
What matters today
- Oil Pulls Back After Trump Holds Off on Iran. President Trump ruled out an immediate U.S. attack on Iran, saying "There will not be a strike today." After that, WTI crude fell 2.06% to $101.14 per barrel, while Brent crude declined 1.80% to $114.62 per barrel . That comes after Friday's session, when energy (XLE) gained 2.60% and was the only sector to clearly lead. The risk hasn't gone away: the US and Israel have drafted plans for Iran strikes after the Nov. 3 midterms, The New York Times reports , and Houthi missile and drone attacks targeted Saudi Arabia on Monday . Trading impact: energy names that led Friday could give back gains if the drop in crude holds, while headlines from the Gulf can still flip that within minutes.
- Fed Week: A Hold Is Expected, So Watch the December Signal. The October FOMC meeting is scheduled for October 27–28, 2026, with the rate decision announced on Wednesday, October 28, 2026, at 2:00 PM ET. The CME FedWatch Tool puts the odds of a hike this week at 9% and the odds of one in December at 84% . Markets expect rates to stay at 3.75% to 4%, although Bank of America expects a quarter-point increase. Rates are already a pressure point, with the US 10-year yield at 4.965 . Trading impact: Fed Chair Kevin Warsh's press conference may matter more than the decision , so rate-sensitive stocks may trade quietly until Wednesday afternoon.
- Big Earnings Week Starts With a Verizon Beat. About one-third of S&P 500 companies are scheduled to report earnings this week . Microsoft and Alphabet report Wednesday after the close, a few hours after the Fed's rate decision, and Amazon follows Thursday evening. This morning, Verizon reported mobility and broadband service revenue of $23.5 billion, up 2.9% year over year and raised full-year 2026 guidance for the third quarter in a row . Analysts had expected EPS of $1.28 . Trading impact: VZ is the opening read on communication services (XLC), which fell 1.78% Friday, while the AI-spending names may stay choppy until the hyperscalers report.
- Options Flow Leans Bearish on Megacaps, Bullish on Micron. Overall net call premium came in at -$105.4M against +$71.8M in net put premium. AAPL (-$56.4M), QQQ (-$32.1M), TSLA (-$22.4M), NVDA (-$21.6M) and GOOGL (-$19.0M) saw the heaviest bearish flow. MU stood out on the other side at +$51.9M, after it rose 2.46% to $877.55 on Friday , a move tied to a BNP Paribas note on memory constraints in AI inference, after a 6.26% drop on October 22 . SPY (+$39.5M), MDB (+$13.8M) and MRVL (+$12.5M) also drew net bullish premium. Dealer positioning data is unavailable today. Trading impact: the gap between bearish flow in Apple and Alphabet and bullish flow in memory and semis makes single-stock moves more likely than a broad index move ahead of GOOGL's report.
- Light Data Calendar After a Defensive Week. Today's schedule is the 8:30 AM ET National Activity index for September, 10:30 AM ET Dallas Fed manufacturing index for October, and a 1:00 PM ET US Treasury sale of $69B in 2-year notes . Shares of two AI-infrastructure names fell around 3% in premarket trading, and IREN and Applied Digital dropped 2.6% and 1.5% . That follows Friday's split session, when tech (XLK +0.49%) and energy held up while consumer staples (XLP -1.92%), consumer discretionary (XLY -1.66%) and financials (XLF -1.32%) led the declines. Trading impact: with little data due, the 2-year auction and oil moves are the main things likely to move markets before Tuesday.
Options flow
| MU calls (strike/expiry n/a) Biggest bullish name in Friday's flow. Flow showed $46,523,975 in net call buying alongside $5,389,347 in premium collected through net put selling . | $51.9M net bullish |
| AAPL calls (strike/expiry n/a) Biggest bearish lean of the session, bearish — call selling drove most of it. | -$56.4M net bearish |
| SPY (strike/expiry n/a) Index flow tilted bullish even though overall call premium across the market was net negative. | $39.5M net bullish |
| QQQ (strike/expiry n/a) Tech-index flow went the opposite way from SPY. TSLA, NVDA and GOOGL were also net bearish. | -$32.1M net bearish |
| MDB calls (strike/expiry n/a) A mid-cap software name with heavy flow: $11,655,188 in net call buying alongside $2,180,035 in premium collected through net put selling . | $13.8M net bullish |
| Note Prints by strike, expiry and fill side aren't available this morning. Rows show each ticker's net premium from Friday. | Alertsify is copy trading software for options and stocks, not an RIA or broker-dealer. This post is for information only and is not investment advice. More from the blog
|