Daily Briefing
Market Briefing, Nov 6, 2026: Nasdaq in Correction, Payrolls at 8:30 AM
~7 min readAlertsify Team
Market Briefing, Friday, November 6, 2026
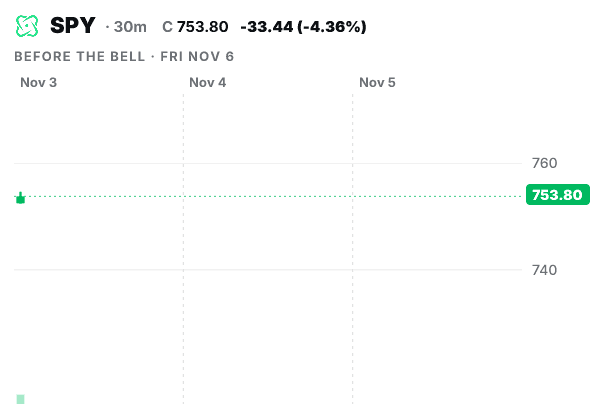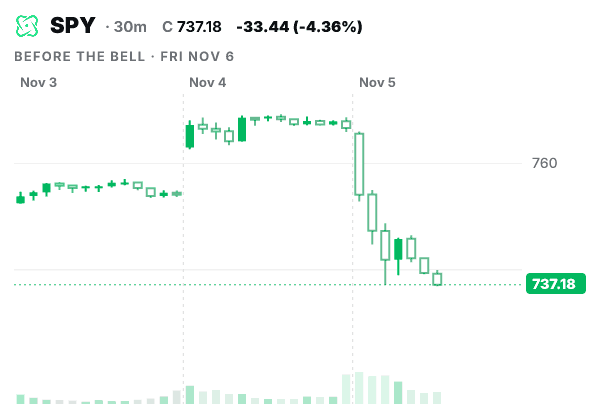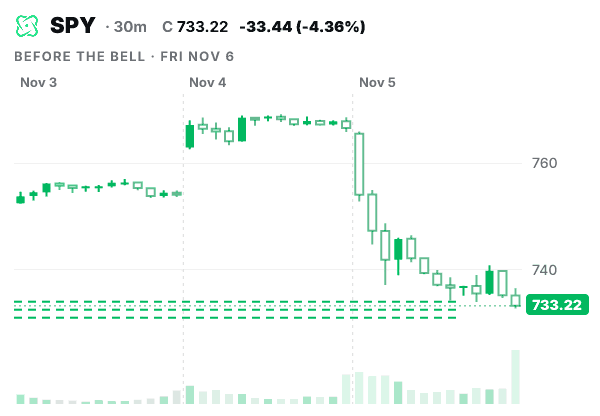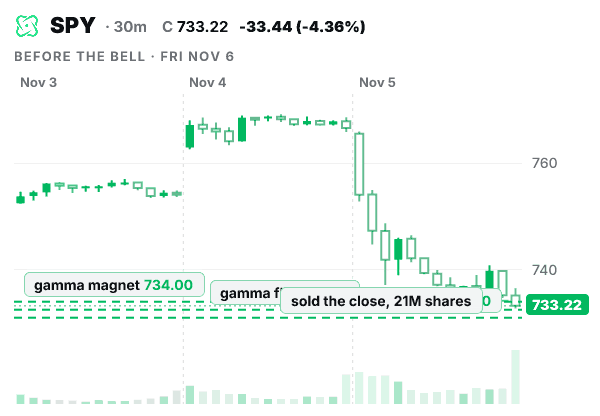
Futures are trying to steady after a brutal AI-driven tech sell-off that wiped out the massive post-election rally from the previous day and sent the Nasdaq Composite into correction territory . Every sector finished lower, with tech (XLK) down 8.00%, and options traders leaned hard to the bearish side: net call premium came in at -$963.1M. Today comes down to the 8:30 a.m. October jobs report. Strategists flag it as a key risk for investors, along with concerns that they may be underestimating how restrictive U.S. monetary policy needs to become .
Market setup
| S&P 500 futures (as of 5:35 a.m. ET) | +0.27% |
| Nasdaq 100 futures, bouncing after Thursday's correction | +1.35% |
| Dow futures | -0.82% |
| Russell 2000 futures (E-mini, overnight) | 2,729.00 (-0.23%) |
| 10-year Treasury yield (6:23 a.m. ET), up from a 4.837% prior close | 4.859% |
| WTI crude, down as .-Iran diplomatic deal eased concerns about potential supply disruptions | $89.77 (-0.83%) |
| Bitcoin: the tech rout triggered $1.25 billion in crypto liquidations, while U.S. spot Bitcoin ETFs recorded $430 million in outflows | $75,710 (-5.83%) |
| Gold (latest available quote, overnight) | $4,056.00 (-1.40%) |
Key levels (dealer gamma)
| SPY (spot ~737) | Call wall 750 (then n/a) · Put wall n/a |
| QQQ (spot ~660) | Call wall 700 (then n/a) · Put wall 650 (then n/a) |
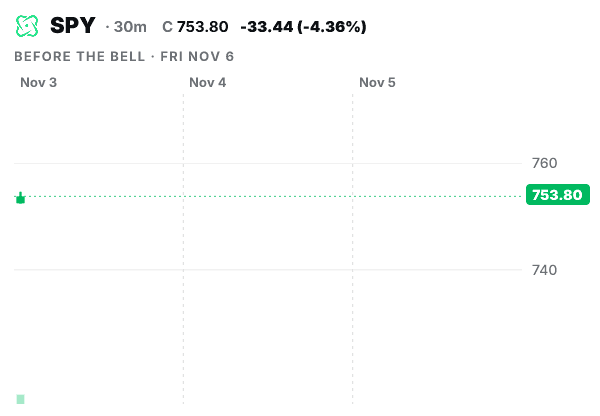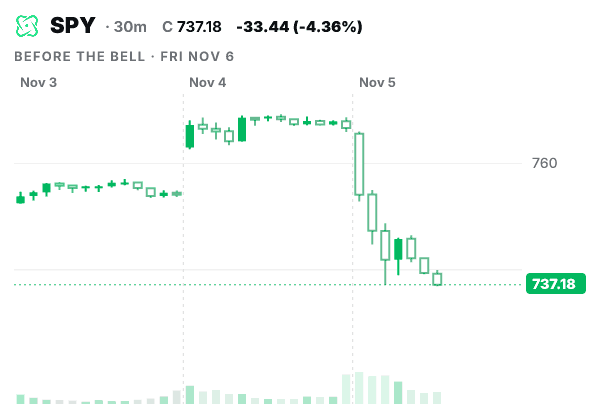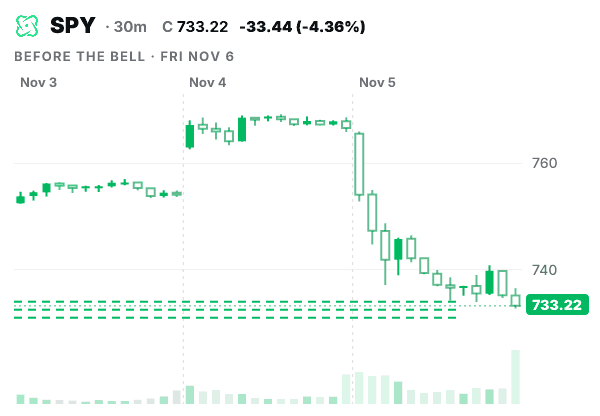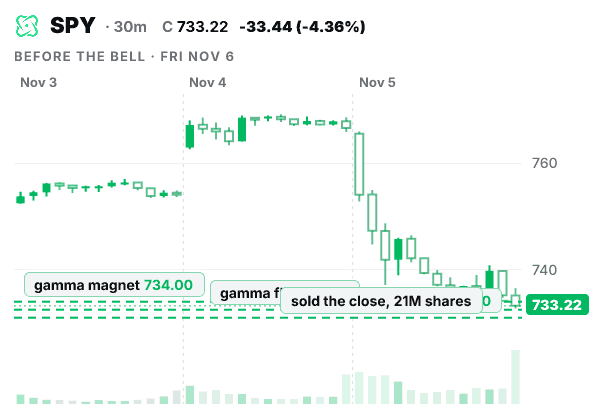
Call walls mark where dealer positioning may slow rallies. Put walls mark where dealer hedging may cushion dips. Both are positioning estimates, not guarantees. Pre-market spot was SPY at 737.4 (+0.6%) and QQQ at 659.8 (+2.0%) . The SPY 750 level is a 40-day call wall. No reliable SPY put wall or second-tier levels were available today, though the heavy strikes in SPY (740, 735, 730, 725) and QQQ (660, 650) are where hedging is most sensitive . The QQQ levels come from Thursday's close, which had a Call Wall at 700, Put Wall at 650, and net dealer GEX of -4.34 $Bn per 1% move . That means dealers are short gamma, so moves can speed up rather than slow down.
Today's market calendar (ET)
| 8:30 AM | Payrolls 55K (prior 29K) |
| 8:30 AM | Jobless rate 4.2% (prior 4.2%) |
| 8:30 AM | Hourly pay m/m 0.3% (prior 0.1%) |
| 8:30 AM | Hourly pay y/y (prior 3.0%) |
| 9:10 AM | St. Louis Fed's Musalem speaks |
| 10:00 AM | UMich sentiment 47.2 (prior 46.3) |
| 12:15 PM | Fed Gov. Bowman speaks |
| 3:00 PM | Consumer credit $11.5B (prior $8.3B) |
Notable earnings
Already reported: Airbnb (ABNB) reported quarterly earnings of $3.16 per share, which beat the analyst estimate of $2.84 , and revenue of $4.87 billion also beat the Street. Microchip (MCHP) reported upbeat financial results for the second quarter, but issued third-quarter guidance with its midpoint below estimates .
Still ahead before the open: Charter (CHTR) is expected at $7.91 per share on revenue of $14.81 billion . Humana (HUM) is expected to post a loss of $1.00 per share on revenue of $40.89 billion . For Moderna (MRNA), analysts expect a loss of approximately $1.10 per share on revenue of $890 million . Fluor (FLR) is expected to post quarterly earnings of 80 cents per share on revenue of $4.16 billion . Oklo (OKLO) and TeraWulf (WULF) also report this morning.
After the close: It's a light Friday, with only HE, TOMZ reporting after the close . Options-implied expected moves for Hawaiian Electric (HE) and TOMZ are unavailable today.
Congress corner
- Sen. Sheldon Whitehouse (D-RI): sale of Amgen Inc (AMGN), $15,001 to $50,000, made October 15, 2026 . He also disclosed a Microsoft (MSFT) sale dated Oct 15.
- Rep. John McGuire (R-VA): buys of Micron (MU), $1K - $15K each, on Sep 24, Sep 25 and Oct 1, 2026, plus a partial sale of Broadcom (AVGO), $1K–$15K, on Sep 24.
- Rep. Thomas Kean (R-NJ): bought ESAB (ESAB), $1K–$15K, on Sep 29, 2026. Partial sales, each $1K–$15K: Johnson & Johnson (JNJ) on Sep 30, Mondelez (MDLZ) on Sep 23 and Abbott (ABT) on Sep 17.
These are delayed disclosures, not real-time trades. Under the STOCK Act, members are required to disclose financial transactions they execute that exceed $1,000 within 45 days .
Social-media trends
Retail chatter is still focused on AI and semiconductor names, even after the sell-off. On r/wallstreetbets, Micron (MU) leads with 673 mentions, Nvidia (NVDA) carries bullish sentiment, and SanDisk (SNDK) is climbing. AppLovin (APP) is the breakout name: over the past 24 hours, mentions of Applovin have surged by an impressive 1440% . Options flow looks split. Net premium was heavily bearish in QQQ (-$286.8M), NVDA (-$150.9M), MU (-$78.4M) and TSLA (-$75.9M), while money went the other way into BE (+$50.5M), APP (+$34.6M), NBIS (+$23.6M), INTC (+$22.5M) and HOOD (+$20.8M).
What matters today
- AI Trade Breaks After the Midterms. The Nasdaq Composite declined 5.52% to close at 24,315.00. The tech-heavy index slid into correction territory, falling more than 10% below a record set last month. A gauge of US semiconductor stocks plunged 12% to notch its worst day since the onset of the Covid-19 pandemic in March 2020. Every sector closed lower in our data, and technology was hit hardest at -8.00%, compared with -0.59% for communication services, the smallest decline. The trigger was fears that Democratic control of the US Congress could lead to tougher AI regulation . Trading impact: semis and AI-infrastructure names will probably keep moving the most in either direction today.
- Chips Bounce Premarket, Dow Lags. Nasdaq 100 E-mini futures rose 1.46%, or 390 points, ahead of the opening bell. Nvidia gained about 4% after plunging 9.26% on Thursday. Other chip stocks, including AMD, Intel, Broadcom and Micron Technology, were up between 5% and 8.3% following steep losses in the previous session , but Dow futures edged lower. Overnight, South Korea's Kospi plunged by almost 9% at the market open on Friday, triggering a trading halt on the exchange for 20 minutes. Trading impact: a bounce this size after a correction can fade quickly once cash trading opens, so watch whether the chip gains hold.
- October Payrolls at 8:30 AM. The forecast is +55,000 jobs after September's +29,000, with unemployment expected to hold at 4.2% and average hourly earnings expected to rise 0.3% m/m after 0.1%. Outside surveys run higher: economists expect 59,000 to 65,000 new jobs after September's 29,000, in surveys by Dow Jones and Reuters . ADP said private employers added 86,000 jobs in October. Trading impact: a big miss or beat on payrolls or wages could swing the open away from the premarket chip bounce.
- December Hike Odds Under Review. On Wednesday, October 28, the Federal Reserve kept its benchmark rate at 3.75%–4%. Since then, the odds of a rate hike fell to 67% from more than 80% in prediction markets after the midterms. Musalem speaks at 9:10 AM, the UMich preliminary survey comes at 10:00 AM (forecast 47.2 vs. 46.3 prior), and Bowman speaks at 12:15 PM. Musalem has said recently that additional policy tightening is needed soon. Trading impact: Fed comments today may move rate expectations ahead of Tuesday's CPI, where the prior reading was 3.7% y/y.
- Options Flow Leaned Bearish. Net call premium was -$963.1M and net put premium was +$287.3M. The heaviest outflows were in QQQ (-$286.8M), NVDA (-$150.9M), SPCX (-$81.3M), MU (-$78.4M), TSLA (-$75.9M) and SMH (-$67.0M). The main exceptions were BE (+$50.5M), APP (+$34.6M) and NBIS (+$23.6M). Dealer gamma data is not available today. Trading impact: the premarket bounce is running against bearish flow in the same tech names, so check whether flow turns once the session opens.
Options flow
| QQQ had the largest net premium outflow of any ticker last session, the biggest single reason the market tide skewed against calls. | -$286.8M net |
| NVDA had the heaviest net outflow among single stocks, matching the weak tone in semis, where SMH and MU also printed large negative totals. | -$150.9M net |
| SPCX had the third-largest net outflow on the tide board, ahead of every single-name chip stock except NVDA. | -$81.3M net |
| MU added to the semiconductor outflows, just ahead of TSLA's -$75.9M. | -$78.4M net |
| BE had the largest net inflow on the board, ahead of APP (+$34.6M) and NBIS (+$23.6M). | +$50.5M net |
| Contract detail such as strikes, expiries and ask/bid side isn't available today, so the rows above show last session's net premium by ticker. | Unavailable |
Alertsify is copy trading software for options and stocks, not an RIA or broker-dealer. This post is for information only and is not investment advice.
More from the blog
Daily Briefing
Market Briefing, Nov 5 2026: Dow Jumps 3% as Chip Stocks Slide After Midterm Sweep
Dow futures rose 0.6% after the index jumped 3.03% on Wednesday, while Qualcomm and Arm earnings weighed on chipmakers and market breadth stayed narrow.
Daily Briefing
Market Briefing, Nov 4 2026: Futures Reverse After Democrats Sweep Congress, AMD Beats
Futures recovered from an overnight drop after Democrats won both chambers of Congress and President Trump said he would accept the results. AMD beat third-quarter forecasts, and AppLovin and Qualcomm report after the close.
Daily Briefing
Market Briefing, Nov 3 2026: Midterm Day Keeps Stocks Cautious as Apple and AMD Weigh
US stock futures are split on Election Day as Apple's memory-cost margin warning weighs on tech. AMD reports after the close, and midterm results are due tonight.